Michael Vittatoe
Managing Partner / Loan Officer
NMLS #1906987We put your loan in front of multiple wholesale lenders and let them compete, then show you what each one does to your rate, your monthly payment and your cash to close.
1st Advantage Mortgage is a licensed mortgage broker and lender in Charlotte, NC. That is the whole point of the two licenses. As a mortgage lender and broker, we compare offers from multiple wholesale lenders on every purchase and refinance across the Charlotte metro, so you can review rates, fees, and program fit before choosing a loan.
Low-down-payment programs, state assistance and a pre-approval that makes your offer competitive.
Lower the rate, shorten the term, remove mortgage insurance or take equity out. We’ll show you the break-even.
Financing structured around the property’s numbers as well as yours, for second homes and rentals.
Drag the sliders for a realistic monthly principal and interest figure. No sign-up, no credit pull, no phone number required.
Estimate monthly principal & interest
Estimate only. Principal and interest shown; taxes, insurance, HOA and mortgage insurance are not included. Not a commitment to lend. Rates and terms are subject to change and depend on credit profile, property and program eligibility.
Buying or refinancing a home in Charlotte should feel straightforward, even in a competitive housing market. Our team helps buyers and homeowners navigate the mortgage process with clarity, speed and personal guidance from start to finish. Whether you’re purchasing in Uptown, Ballantyne, SouthPark or anywhere in Mecklenburg County, we make securing financing efficient and stress-free.
As a broker, we put every file in front of several wholesale lenders rather than fitting borrowers to one institution’s product. That means we can matchThat means we can match your credit profile, property type and down payment goals to the program that actually fits.
Having a pre-approval letter in hand before you start shopping puts you in a much stronger negotiating position. We turn most pre-approvals around within 24 hours, and when you’re in a competitive offer we’ll speak to the listing agent directly to confirm your file is solid.
Rising home values across Mecklenburg County have created significant equity for many homeowners. Refinancing can remove mortgage insurance, shorten your term, consolidate higher-interest debt or fund renovations. We’ll run the numbers and tell you exactly when you break even.
From South End and Ballantyne to Huntersville, Concord, Belmont and Mount Holly, plus Fort Mill and York County across the state line.
Every file goes out to several wholesale lenders, so the program you end up with is picked from real offers rather than one lender’s menu.
Flexible down payments, no upfront mortgage insurance. The common route for solid credit.
Government-backed and more forgiving on credit. Strong for first-time buyers.
For veterans, active military and surviving spouses. A program with features that may matter to eligible borrowers.
Zero down for qualifying properties outside the metro core. Income limits apply.
Financing above the conforming limit, with stricter credit and reserve requirements.
Structured around the property’s numbers as well as yours.
A lower initial rate for a fixed period. Worth running if you may move or refinance.
Bank statement, DSCR, asset depletion and 1099-only programs for self-employed buyers and investors.
Bank statement, 1099-only, asset depletion and DSCR programs for buyers whose income is real but does not sit on a W-2.
Compare any two programs side by side: credit score, down payment, mortgage insurance and occupancy rules, in one table.
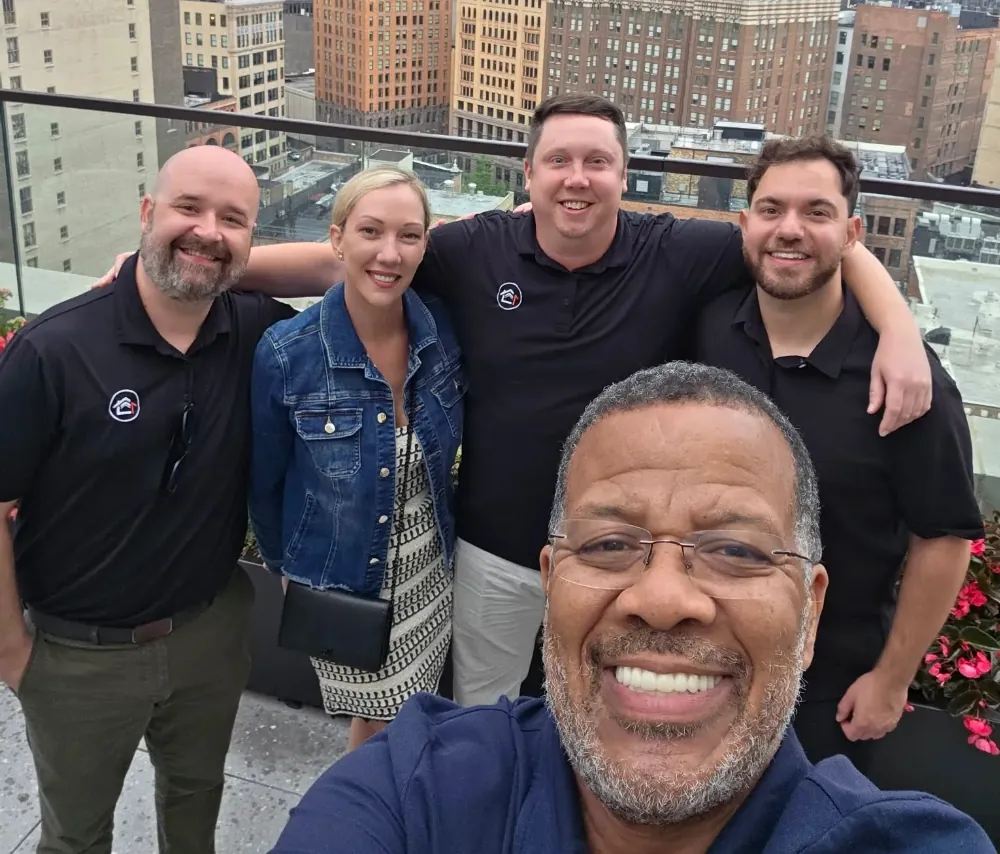
Licensed loan officers across all six states we serve. Every one has a direct line and their own NMLS number.

Managing Partner / Loan Officer
NMLS #1906987
Managing Partner / Loan Officer
NMLS #1381403
SVP of Mortgage Lending
NMLS #1608479
Senior Loan Officer
NMLS #1643314
Senior Loan Officer
NMLS #1643299


Senior Loan Officer
NMLS #1009680
Senior Loan Officer
NMLS #1995940


Loan Officer
NMLS #178431


Loan Officer Assistant
Non-licensed role
Engagement Director
Non-licensed roleThere’s a difference between a national call center and a local broker and lender who knows what a home in Ballantyne appraises for, which builders are behind schedule in Belmont, and which listing agents call back on a Sunday.
When you’re in a competitive offer, a broker who can call the listing agent directly and confirm your pre-approval is solid is often the difference between winning and losing the house.
The same five steps every time, so you always know where you are.
A short conversation about goals, income and credit. Usually turned around within 24 hours.
Your agent and our team stay in contact while you look, so an offer can move fast.
Under contract, we compare lenders and programs against your full financial picture.
Documentation, appraisal and underwriting, with updates throughout, not just at the end.
Final numbers reviewed before closing day. No surprises at the table.
Published through Trustindex, which reads them straight from Google. We do not pick which ones show and we cannot edit them.
Credit score requirements vary by loan program and overall financial profile. Most conventional home loans typically require a minimum score around 620, while government-backed programs such as FHA, VA, and USDA may allow lower scores depending on qualifications and compensating factors. Rather than focusing on a single number, we evaluate your full financial picture to determine the home loan options available to you. If you are not there yet we will tell you honestly what needs to change and roughly how long it takes.
Income requirements depend on your debt-to-income ratio (DTI), credit profile, and loan type. Most programs allow a DTI between 43% and 50%. We help structure mortgage approvals to maximize purchasing power while keeping payments manageable.
Most home purchases close within 21 to 30 days, depending on the loan type and documentation. Our team works closely with buyers and real estate agents to ensure smooth, on-time closings.
1st Advantage Mortgage compares offers from multiple wholesale lenders on every file instead of fitting borrowers to a single institution’s product. This gives borrowers a way to review interest rates, guidelines, and financing options for their situation.
Refinancing may make sense when interest rates drop, when you want to reduce monthly payments, shorten your loan term, or access home equity through a cash-out refinance. We help homeowners evaluate break-even points and long-term savings before making a decision. If it does not make sense, we will say so.
Most cash-out refinance programs allow homeowners to access equity while maintaining at least 20 percent ownership in the property. Loan limits and guidelines vary by program and market conditions.
Yes. First-time homebuyers may qualify for low down payment options, down payment assistance, and competitive interest rates through FHA, VA, and conventional programs. We help buyers understand all available options before choosing a loan.
Most mortgage applications require recent pay stubs, W-2s or tax returns, bank statements, identification, and employment verification. Our process is designed to keep documentation simple and approvals efficient, and your loan officer will send you a specific list once we know which program you are using.
Usually within 24 hours. We start with a short conversation about your goals, income and credit, then issue a pre-approval letter you can put in front of a seller.
It depends on the program. VA and USDA loans can require nothing down for eligible borrowers, FHA starts at 3.5%, and conventional loans offer a range of options. We'll walk you through what each one means for your monthly payment.
Often, yes. Rising home values across Mecklenburg and Gaston County have built equity for many homeowners, and a refinance can remove mortgage insurance entirely.
Charlotte and Mecklenburg County, Gaston County including Belmont, Gastonia and Mount Holly, and across the state line into Fort Mill and York County. We're licensed in North Carolina, South Carolina, Texas, Florida, Virginia and Pennsylvania.
A five-minute conversation tells you what you’re working with. No credit pull to start.
¹ No-Down Payment Disclaimer: Closing costs and fees may still apply.
² Representative example (conventional, fixed rate): Purchase price $300,000 with a 5% down payment of $15,000 and a loan amount of $285,000. 30-year fixed rate at 6.000% (6.390% APR). 360 monthly principal-and-interest payments of $1,708.72, plus estimated private mortgage insurance of $95.00 per month until the loan balance reaches 78% of the original value (approximately 129 months). APR reflects $1,995 in lender fees, 15 days of prepaid interest, and mortgage insurance. Payment does not include property taxes, homeowners insurance, or HOA dues; your actual payment will be higher. The interest rate is fixed and will not increase. Example dated September 12, 2026, for illustration only. Rates change daily. This is not an offer, quote, or commitment to lend. All loans are subject to credit approval, property appraisal, and program eligibility. Your rate, APR, and payment will depend on your credit, down payment, property, and loan program.
³ Refinancing Disclaimer: When refinancing your mortgage, you can typically reduce your monthly payment amount. However, your total finance charges may be greater over the life of your loan. Your 1st Advantage Mortgage loan professional will provide you with a comprehensive refinance comparison analysis to determine your total life loan savings.
⁴ VA Mortgage Disclaimer: VA home loan purchases offer options for a 0% down payment, no private mortgage insurance requirements, and competitive interest rates with specific qualification requirements. VA Interest Rate Reduction Loans (IRRRL) are exclusively for veterans with current VA loans. Current loan rate restrictions apply, and limits to recoupment of costs and fees apply. VA cash-out refinances are available for veterans with or without current VA loans. Policies and guidelines may vary and are subject to individual borrower(s) qualifications. Program and lender overlays apply.
⁵ Down Payment Assistance Disclaimer: First-lien interest rates may be higher when using a DPA.
⁶ Pre-Approval Disclaimer: Pre-approvals are granted to clients who meet qualifying approval criteria and specific loan requirements at the time of application. Results may vary.
General Disclaimer: The content on this page has not been approved, reviewed, sponsored, or endorsed by any department or government agency.