
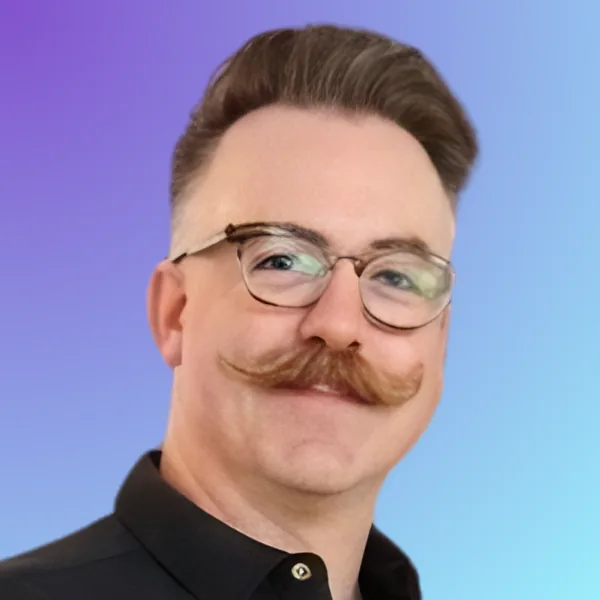
Christopher Germain works under NMLS 1643299. The firm’s town pages list him on Belmont, Mount Holly, Indian Trail, Kannapolis, Fort Mill and Rock Hill. That set is not random. It puts him on both sides of the Carolina line, where a weekend of showings can produce two tax systems and two closing customs. He also takes files in Charlotte, Concord, Huntersville and Gastonia.
Call (704) 460-3349 or write christopher@firstadvantagemortgage.com. Wholesale pricing for his files is run from the brokerage’s suite 1933 inside 128 South Tryon’s uptown building.
Kannapolis and Rock Hill can look similar and still close differently
Kannapolis sits in North Carolina, with taxes expressed the way North Carolina towns publish them, per hundred dollars of assessed value. Rock Hill sits in South Carolina, where owner-occupants often ask about South Carolina’s owner-occupant tax filing. Christopher will not treat a lower list price in one of those cities as proof of a lower payment. He wants the tax line and the closing custom on the table before you pick a favorite listing photo.
If Rock Hill is in play, read the legal residence explainer and the Rock Hill guide. If Kannapolis is in play, start with the Kannapolis page. Then email him both street addresses so he can turn that reading into two actual payments.
Fort Mill, Indian Trail and the Gaston river towns
Fort Mill adds another South Carolina attorney closing, often for buyers who work in Charlotte and want a shorter hop than a farther-flung suburb. Indian Trail pulls him into Union County, North Carolina, with its own tax mix and a lot of subdivision HOAs. Belmont and Mount Holly sit along the Catawba on the Gaston County side, where a river-town commute and a different price band change the file again.
Christopher’s habit is to ask which of those places you would actually accept tomorrow. A five-town search sounds flexible until underwriting, insurance and cash to close have to be estimated five different ways. Narrowing to two real contenders lets him price something an agent can use.
What he compares once the town is named
He handles both purchase work and refinance work. A given file may call for conventional financing, jumbo pricing, an FHA path, a VA path, first-home financing or an investment-property structure if you will not occupy the house. He lines up competing wholesale quotes so cost and calendar are both visible. Occupancy is the first fork: living there, keeping a second home or renting the property out are not the same conversation.
Military households can review the VA overview and then request that path in the first round of numbers. Owners thinking about replacing a current loan should look at the refinance decision guide and arrive with a recent statement plus an honest timeline for staying put.
Detail work that keeps a border file from slipping
Christopher is known inside the firm for walking through how lenders’ options differ before you choose one, and for staying precise about conditions once underwriting starts. On a file that crosses the state line, that precision matters. Appraisal instructions, insurance questions and title work all follow the property’s state, not the office where he sits.
Support staff still gather paperwork and schedule outside vendors. Christopher remains the officer who tells you why a condition appeared and what it changes about approval or cash to close. You keep his number after the pre-approval letter goes out.
Starting a file with Christopher
Call (704) 460-3349 or email christopher@firstadvantagemortgage.com. The profile field on this page reaches him. Name the two towns you are most serious about, and say which state each parcel sits in. If one is in South Carolina and one is in North Carolina, put that in the first sentence.
Look up 1643299 on NMLS Consumer Access to open his personal file. The company file is 2468711. Read the personal one before you count on him for a South Carolina address.
If another colleague is a better match, open the staff list.
How he likes a two-state house hunt to be sequenced
Christopher would rather you pick two real finalists than keep seven towns “in the mix.” Each town means a different tax estimate, a different insurance quote and, when the state changes, a different attorney custom. Pricing all seven loosely produces a letter that is hard for an agent to defend. Pricing two carefully produces something you can actually offer with.
On Indian Trail files he also asks about the HOA early, because dues belong in qualifying and project documents can slow a townhome or gated-street purchase. On Belmont and Mount Holly files he asks about the commute you will actually drive, not the one that looks short on a Saturday. Fort Mill files need the South Carolina closing custom named out loud so no one expects a North Carolina due diligence period on a York County contract.
If you already lost a house because financing felt late, tell him what slipped. Appraisal timing, insurance and title each fail in different ways on border files, and he would rather hear the last story than guess which part broke.
Bring any prior denial or delayed closing story in writing if you have it. A short timeline is more useful than a general feeling that the last lender was slow.
If one spouse works in North Carolina and the other in South Carolina, mention both workplaces. Commute tolerance often decides the town more honestly than a list of amenities, and he would rather hear that constraint up front.