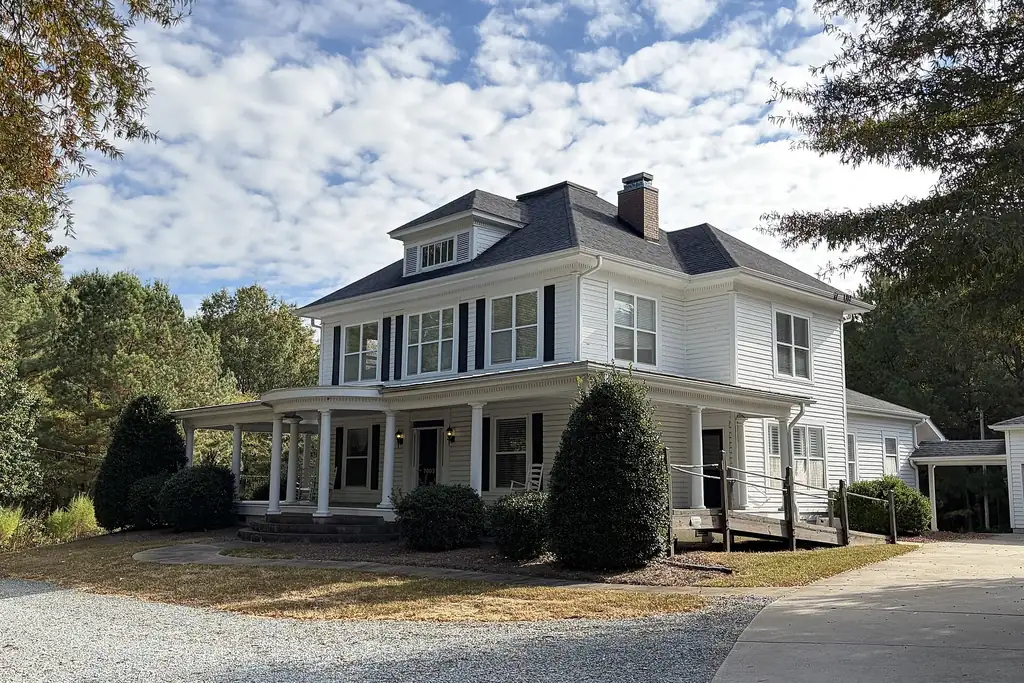
The first question we ask a Weddington shopper is not about rate. It is about the land. Custom homes here often sit on wells and septic. Some include extra acreage, a barn or other outbuildings. Certain investors limit how much of the appraised value they will attribute to land, and they may want a specialized appraisal. Telling us about acreage before we pick a channel keeps a file from stalling after you are already under contract.
From Uptown Charlotte (128 S Tryon, office 1933) we work as a North Carolina mortgage broker, Company NMLS 2468711. One application feeds several wholesale investors, including desks that regularly purchase large loans secured by wells, septic systems, gated golf streets and equestrian property.
When the land is part of the underwriting story
Equestrian properties and other large tracts can run into a land-value haircut if we send the file to an investor that prefers a house on a standard lot. That is a solvable problem when we know about it early. It is an ugly surprise when it appears in an appraisal review. Gated and golf communities add another layer: association dues and reserve questions that high-balance underwriters will want to see in qualifying.
Near the Waxhaw and Marvin lines, confirm which town and which school assignment actually apply. Providence Road, Weddington Road and Weddington-Matthews Road connect the town to south Charlotte, Ballantyne and Matthews. Children here attend Union County Public Schools; confirm the campus for the specific property, especially near those edges.
Almost every house is detached, and many use well and septic
Census Reporter counts 13,805 residents. The typical owner-occupied house is valued at $824,100, the top median among towns we serve near Charlotte and nearly double the county figure of $417,300. Typical household income is $190,766, against $102,900 countywide. About 95 percent of households own. Detached houses are 98 percent of the stock, far above the county’s 86 percent. The construction midpoint is 2000, matching Union County as a whole.
About 74 percent of owners still have a loan. The midpoint tax they reported is $3,990, well above Union’s $2,396, which shows that value, not a heavy town levy, drives the bill. Gross rent centers near $1,927. The typical owner arrived around 2012. Wells and septic are common on custom lots and are financeable. They do change the inspection and the appraisal, and septic capacity matters if you plan to add a bedroom or an accessory dwelling.
A 3.5-cent levy on an $824,100 midpoint
Inside town the published 2026-27 total is $0.4692 on every $100 of value, built from Union’s $0.4342 plus the town’s 3.5-cent piece, one of the lowest municipal levies in the region. Plan on about $469 yearly for every $100,000 on the tax card. Scaled to $400,000 of tax value, the yearly piece is about $1,877. Many actual purchases sit far above that illustration because the owner midpoint is $824,100, so the dollar bill can still look large even with a tiny town rate.
Union last reappraised in 2025, which already reset values countywide. We still read the Weddington card because a custom house on acreage may not track the town average. The statewide billing calendar appears in our property-tax explainer.
One improvement away from a jumbo file
The $824,100 owner midpoint sits close enough to the 2026 conforming ceiling published by FHFA ($832,750) that a modest upgrade, a closing-cost roll-in or a stronger-than-list offer can push a file out of conforming territory. A loan amount above $832,750 is treated as jumbo, and each investor writes its own standards for credit, cash reserves and paperwork. In Weddington that conversation is the ordinary file, not a special case reserved for a handful of estates.
We shop several high-balance channels because reserve rules and the way desks treat acreage or well-and-septic collateral can decide the outcome more than a small rate gap. Loans that stay under the cap can still use conventional financing. FHA’s 2026 maximum sits well below many Weddington prices, so it seldom fits. Eligible veterans should still consider VA financing even when the balance is large, because VA can remain available there. Details on overlays live on our jumbo page.
The paper trail high-balance desks want to see
Plan on two years of tax returns, full statements for every asset account you will use, and a clear path through bonus, commission or business income. Households relocating from south Charlotte often arrive with pay that is not a single salary figure. Bank statements can carry the file when tax returns tell an incomplete story. We would rather sort that trail before an offer is written than after.
Cash-to-close help of the kind we discuss on more affordable Union County pages is rarely the story here. The constraint is usually documentation and reserves, not a thin down payment. If a listing happens to be a smaller product near the town edge, we can still compare lender-run assistance, but we do not treat it as the default Weddington path.
A town of about 13,800 where nearly every house stands alone
Weddington counts 13,805 residents on Census Reporter’s latest five-year figures. It is small compared with the cities people drive to for work, and that smallness is the point: the town has stayed a landscape of large lots and custom houses rather than a builder grid. About 98 percent of the homes are detached, so almost every appraisal is a house-to-house comparison rather than a condo project review. Household earnings center on $190,766. Those two facts together explain why so many files here involve larger down payments, extra reserves and an appraiser who has to understand acreage, not just heated square footage.
At $824,100, the ACS owner-value reading is the highest among the nearby towns we write about, which is a different claim from Davidson’s position as the highest midpoint inside Mecklenburg County. Most purchases at that level test the 2026 conforming cap of $832,750 or cross it. The construction midpoint around 2000, with many owners dating their move-in to about 2012, describes a place people moved to after they had already bought somewhere else, then stayed. That is why the first call is so often about selling a current house as well as buying this one, even though the headline numbers look like a simple high-balance purchase.
Why a south-Charlotte tour and a Weddington tour are not the same tax file
Households often tour south Charlotte and Weddington in the same month because the drive times can look similar on a map. The governments do not. A Weddington parcel sits in Union County, uses the 3.5-cent town levy on top of Union’s $0.4342, and produces a published in-town total of about 46.92 cents. A Charlotte parcel uses the city stack of about 78.57 cents. The land itself may also include a well, a septic system, a barn or a fenced pasture that a south-Charlotte subdivision lot would never present.
We write one letter that already uses the Weddington stack and the extra property features you have told us about, and a second letter if you are still seriously touring inside the city. Mixing the two on a single worksheet hides the reason many buyers cross into Union County in the first place. Golf or gated dues, when they apply, belong on both versions. School assignment stays with Union County Public Schools on this side of the line; verify the campus for the specific street rather than assuming a townwide zone.
Building the letter before you start touring large lots
The opening conversation is about lot type (a custom house on well and septic, a gated or golf street, or acreage with outbuildings) and whether the numbers already assume financing above the conforming cap. We review pay, reserves and credit, then produce a letter sized to that budget rather than a standard conforming note that falls apart if the winning bid crosses into jumbo territory.
Once the house is under contract we send the file to an investor that already handles large-lot collateral, get the appraisal ordered, and lock on a schedule that fits the contract dates. Recording takes place in Union County. Wider county context is on our Union County page. People who already own here and want to recast an existing loan can use the Charlotte refinance overview.
What high-balance Weddington clients have said
Weddington remarks collected from public Google listings appear here unedited.
Data behind the Weddington page
ACS 2020-2024 estimates used here, via Census Reporter, include a $824,100 owner-value midpoint, 13,805 residents, income of $190,766, 95 percent ownership, a 2000 construction midpoint, a 98 percent detached share, a 74 percent financed-owner share, taxes paid of $3,990, rent of $1,927 and a 2012 arrival midpoint, each compared with Union County. The jumbo discussion uses the 2026 conforming ceiling published by FHFA, $832,750. The 2026-27 publication shows Union’s $0.4342, Weddington’s 3.5 cents and the $0.4692 total, and they identify 2025 as the year Union last reappraised. The $1,877 illustration uses published rates on an in-town tax value of $400,000; many actual bills are higher because values cluster near the $824,100 midpoint. Large lots, wells and septic, gated and golf communities, equestrian acreage, the Waxhaw and Marvin edges, Providence Road, Weddington Road, Weddington-Matthews Road and Union County Public Schools were listed on the page before this rewrite.
The payment on a large-lot Union County house
An in-town tax value of $400,000 at $0.4692 is about $1,877 a year, but many purchases sit nearer the $824,100 owner midpoint, so the yearly tax is often larger than that illustration even with a 3.5-cent town levy. Add insurance priced on that house, club or gate dues when a community charges them, and a well-and-septic reserve that a city water customer would not need. Because so many loan amounts sit at or over the conforming ceiling, the quoted rate may itself be a jumbo rate. That gap belongs in the first quote we build.
Reaching equity without disturbing a jumbo first lien
At an $824,100 midpoint, many owners have built a large cushion even if a loan is still in place. A large first mortgage needs extra care if you want to draw cash without refinancing it. The Charlotte HELOC page sets a line of credit next to a closed-end second; the statewide hub adds the refinance comparison. Buying another property before this one sells is a bridge-financing topic.
1st Advantage Mortgage Broker LLC is a Mortgage Broker, not a lender. Company NMLS #2468711 (NMLS Consumer Access), licensed as a mortgage broker by the North Carolina Commissioner of Banks. Equal Housing Opportunity. 1st Advantage Mortgage is not a government agency and is not affiliated with HUD, FHA, VA, USDA or any city or county. This page is general information, not an offer or commitment to lend. All loans are subject to credit approval, property appraisal and program eligibility, and program availability can change. Local statistics are estimates from the sources listed.