
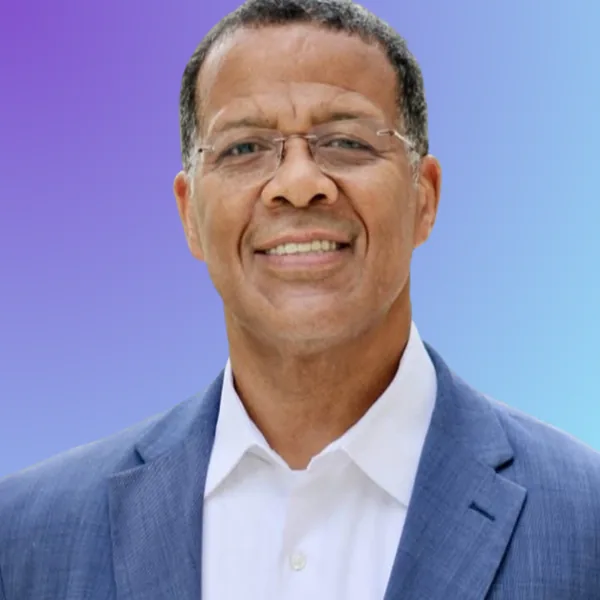
Michael Taylor originates loans at 1st Advantage Mortgage, recorded under NMLS 178431 and separately holds a real estate license. He has helped homebuyers and homeowners since 2009. The combination matters on a live contract: he has sat on both sides of the timeline, so he tends to see where appraisal scheduling, title work and attorney dates usually slip before they become emergencies.
He works with clients in the city, westward through Gastonia and nearby river communities, through Concord, and south into Fort Mill and Rock Hill. The firm’s Huntersville and Weddington pages list him as well, along with Concord. Reach him at (704) 502-4338 or michael.taylor@firstadvantagemortgage.com. The brokerage that backs the file is 1st Advantage Mortgage, working from office 1933 along South Tryon, in Charlotte’s center-city district.
Why the real estate license changes the loan conversation
Plenty of loan officers understand guidelines. Fewer have also held a real estate license and watched a contract from the agent’s side of the table. Michael uses that second viewpoint when he builds a pre-approval and when he maps the days between offer and recording. He knows which dates in a North Carolina due diligence period or a South Carolina attorney closing are doing real work, and which ones only look comfortable on a calendar.
That does not mean he will represent you as a buyer’s agent on the same transaction where he is originating the loan. The two licenses are separate tools. On a 1st Advantage Mortgage file, he is your loan officer. The real estate background is context he brings to coordination with the agent and attorney you already have.
Look up 178431 on NMLS Consumer Access for his mortgage authority, and look up 2468711 for the company. Mortgage licensing and real estate licensing are different systems. The NMLS record is the one that decides whether he can originate the loan on your property.
A map that runs from Gaston County to the South Carolina towns
Michael’s published bio places him with clients in the core city, around Gastonia, along with Belmont and Mount Holly as separate stops, plus Concord and the South Carolina towns of Fort Mill and Rock Hill. The firm’s Huntersville, Concord and Weddington pages also list him. That spread covers older Gaston County streets, Cabarrus County purchases in Concord, lake-adjacent Huntersville files and higher-priced Weddington homes that sometimes need jumbo financing.
Rock Hill and Fort Mill add South Carolina’s tax treatment and attorney-closing custom to the mix. If you are choosing between a Rock Hill house and a Concord house, the listing prices alone will not tell you which payment is heavier once escrow is funded. Michael will run both pictures rather than assume the cheaper purchase price wins.
Useful reading while you narrow towns includes Rock Hill, Huntersville and Weddington.
Purchase and refinance work since 2009
The firm’s published profile for Michael states that he has helped buyers and homeowners since 2009. That is the date we can stand behind, because it already appears on this site. It covers a long stretch of guideline changes, rate cycles and local inventory shifts, and it is one reason he is comfortable flagging places a file usually stalls: appraisal queues, condo questionnaires, gift-fund paper trails and title questions that surface late if nobody asks early.
He originates purchase and refinance loans across FHA, VA, USDA, conventional, jumbo and investment-property financing. Occupancy comes first. A primary residence, a second home and a rental are three different conversations, even when the house looks the same from the curb. Eligible veterans should raise VA eligibility at the outset so a VA loan is priced with everything else rather than discovered later.
Refinances get the same scrutiny as purchases. If you want to change a rate, pull cash out or restructure debt, he will look at how long you expect to keep the house and what the current first mortgage is doing for you. Replacing a loan you are happy with is not automatically the right move.
Keeping a tight closing date honest
When the contract leaves little slack, Michael plans backward from the signing appointment. He wants the appraisal ordered quickly, insurance quoted on the actual address and title work started before anyone assumes the last week will be quiet. His real estate background is most obvious here. He has seen which requests actually take days, and he would rather ask for them at the beginning than discover them after the due diligence period has closed.
You still get processing support from the rest of the firm for collecting documents and scheduling third parties. Michael remains the officer who interprets conditions and talks with your agent when the calendar needs a realistic adjustment instead of a hopeful one.
Contacting Michael Taylor (not Michael Vittatoe)
Two people named Michael work at 1st Advantage Mortgage. This page is Michael Taylor, NMLS 178431, at michael.taylor@firstadvantagemortgage.com and (704) 502-4338. Michael Vittatoe, a Managing Partner, has a different NMLS number and a different email. If you were referred to “Michael” without a last name, check the NMLS number on the card you were given.
The message box on this profile goes to Michael Taylor. Tell him the town, the occupancy and whether signing dates are already written into a purchase agreement you cannot move. If the property is in South Carolina, say that immediately so licensing and closing custom are part of the first reply.
Other officers are listed on the team page. If you want a broader walkthrough of buying in the metro, start with the Charlotte purchase guide.