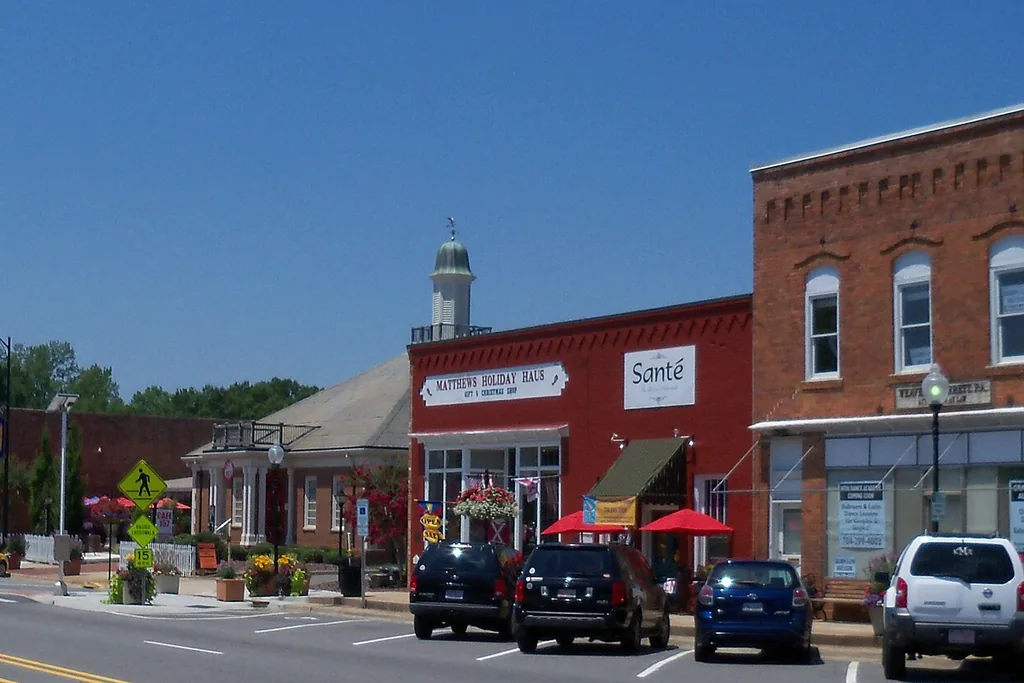
Matthews looks simple from a listing photo: a small downtown, medical offices, a college campus and subdivisions that fan out toward the county line. The loan file is less simple. A Matthews mailing address can sit inside the town, in unincorporated Mecklenburg County or across the line in Union County. Those three situations do not share a tax bill, a school assignment or the same set of extras in your monthly payment.
1st Advantage Mortgage is an independent mortgage broker based at 128 S Tryon St, Suite 1933, in Uptown Charlotte. We are licensed in North Carolina (Company NMLS 2468711) and we compare wholesale lenders on a single application so you can see more than one way to buy the house you actually want.
Start with the parcel, not the ZIP code
The most expensive surprise we see on Matthews purchases is not interest rate. It is finding out, after you are under contract, that the house is not where the mailbox suggested. Some homes that use a Matthews address are in Union County. Others sit outside the town limits even though they share the name. The county tax record, not the listing headline, is the document that tells you who bills you and which school system serves the street.
That check belongs at the start of your search. Charlotte-Mecklenburg Schools cover Matthews homes that sit in Mecklenburg County. A Matthews address on the Union County side is served by Union County Public Schools. Property taxes split the same way. Inside the Town of Matthews during the 2026-27 budget year, Mecklenburg collects 49.27 cents on each $100 the assessor assigns and the town adds 27.95 cents of its own, which totals $0.7722. A $350,000 taxable value in town produces a bill of about $2,703 a year on those rates, using the state’s published 2026-27 local rate tables from the North Carolina Department of Revenue. Move the same assessment outside town or into Union County and the bill changes.
What the numbers say about Matthews itself
Census Reporter, drawing on the Census Bureau’s ACS file that covers 2020 through 2024, counts 30,577 people in Matthews. Owner-occupied homes here have a median value of $445,100, above Mecklenburg County’s median of $406,800. Household income centers on $108,611, compared with $87,005 countywide, and about 64 percent of occupied homes are owned rather than rented.
The housing stock is older than many people expect for a growing suburb. The median Matthews home was built in 1994, three years earlier than the county median of 1997. Detached houses make up 62 percent of homes, 68 percent of owners still carry a loan on the property, and the typical owner moved in around 2011. The Census median real estate tax paid by Matthews owners is $3,047, and median gross rent is $1,764. Those rent figures are the benchmark many first-time buyers here compare against a principal-and-interest quote.
Town-level listing medians are not published separately on this page. For context, Realtor.com’s September 2026 residential data for Mecklenburg County put 4,389 homes on the market, a 17 percent rise versus September 2025. Fresh listings that September numbered 1,490, another 1,776 went pending, and roughly one quarter of the actives showed a reduced ask. Buyers in Matthews feel that shift in longer negotiation windows, not in a collapse of demand around downtown or the I-485 corridor.
Four Matthews locations that change the loan conversation
Downtown around Trade Street and Stumptown Park mixes older houses with newer townhomes. Walking to shops and the farmers market is the draw. The financing detail is HOA dues on the townhomes, which count in your qualifying payment, and older systems on the houses that a thorough inspection should catch before your due diligence date.
The subdivisions off Weddington Road and Matthews-Mint Hill Road are where many families land. Lots are established, streets are quiet and HOAs are common. Ask for the budget and any special assessment prior to submitting a contract, because an extra monthly due can push a conventional file into a higher payment than the listing price implied.
Near I-485 and Sycamore Commons the inventory skews newer, with townhomes and recent construction that suit a shorter commute. Builder incentives show up here. Treat the incentive as a dollar amount in writing and let us price the same loan with wholesale lenders. Sometimes the preferred-lender credit is worth taking. Sometimes the rate or fee on that channel costs more than the credit saves.
Along the Union County line, confirm the jurisdiction first. The house can look identical to one a half mile west and still live in a different tax rate, a different revaluation calendar and a different school system. If you are also looking next door, our Mint Hill home loan guide and the Charlotte mortgage broker page cover those markets in detail.
How commuting and daily life show up in underwriting
Matthews sits on US 74 and I-485. Novant Health Matthews Medical Center and CPCC’s Levine campus are in town, which is one reason healthcare and education employees look here first. The planned LYNX Silver Line would run along US 74 toward Uptown, but it remains in planning with no firm opening date. Do not size a commute or a resale thesis around a train that does not yet have a schedule.
Insurance is the other local variable. Get a homeowners quote on the exact address early, and check the FEMA flood map if the lot sits near a creek or drainage easement. A flood policy, when required, is part of the payment we qualify you to.
What it costs to own, beyond the interest rate
On a $400,000 taxable value inside Matthews, the combined $0.7722 rate works out to about $3,089 a year. Mecklenburg’s previous countywide reappraisal took place in 2023, and every parcel in the county, Matthews included, is scheduled for a new value effective January 1, 2027. If you buy in 2026, your first-year escrow is based on the current assessment. Your second year may not be. Build a cushion rather than assuming the seller’s last bill is your bill forever.
North Carolina property tax runs on a calendar year. The bill arrives with a September 1 due date, and interest does not begin to accrue until after January 5. At closing, the settlement statement credits you for the seller’s share of that year so you are not paying for months you did not own the home. The standard contract also usually assigns the state’s deed excise, one dollar for each $500 of sale price, to the seller (see the excise provision in Chapter 105).
If you want help running the full monthly stack, our metro tax explainer and the insurance overview for both Carolinas are useful companions. For cash due when you sign, see what buyers typically bring to the table.
The cash a North Carolina offer requires in Matthews
A Matthews purchase written on the standard statewide offer used by North Carolina REALTORS members asks for two separate deposits. The due diligence fee goes to the seller when the contract is signed. It is generally not refundable, and it is credited to you at closing if you proceed. In return you get a window during which you can cancel for any reason. Earnest money sits with an escrow agent. After the due diligence date it is at risk if you walk away without a contract reason.
That window is your working time. In Matthews we want three things finished inside it: a home inspection that matches the age of the house (median year built 1994), confirmation of the county and town on the tax record, and a loan approval far enough along that a surprise condition does not appear the week of closing. If the home is a downtown townhome or a subdivision with an HOA, the association documents belong in that same pile.
A licensed North Carolina lawyer handles title work, the signing appointment and the recording afterward. Buyers typically choose that lawyer. If you want the full step-by-step for the metro, the Charlotte home buying guide walks through pre-approval, offers and closing in more depth.
Loan paths that actually show up on Matthews files
Most Matthews buyers land on a conventional or FHA loan. The 2026 conforming limit for a one-unit home here is $832,750 (FHFA) and the FHA ceiling for the county is $541,287 (HUD). The town’s median owner value of $445,100 sits comfortably inside both limits for a typical single-family purchase, so program choice is about credit, down payment and the property, not about hitting a cap.
Eligible veterans and service members should look at VA home loans, which can finance a primary residence with no down payment if the entitlement and the property fit. A few addresses toward the rural edge of the region may be worth checking against USDA maps near Charlotte. Larger purchases go jumbo. Self-employed buyers can use bank-statement qualifying, and investors can look at DSCR or other non-QM options described on our conventional, bank statement and DSCR pages.
If cash to close is the constraint, some wholesale lenders we work with attach their own assistance as a second lien behind an FHA first mortgage. One structure is forgiven if you remain in the home for a set period. Another is repaid over time. A separate grant can sit beside a conventional first mortgage. These are lender programs, not a state housing agency product. We run them next to a plain file so you can see whether the help is cheaper than simply bringing more cash.
Why a single bank is a weak plan in this town
A bank or credit union can offer only the loans it keeps or has already chosen to sell. Matthews files are not all the same. A downtown townhome with HOA dues, a 1990s house that needs a roof, a Union County parcel with a Matthews mailbox and a first-time buyer using gift funds are four different underwriting conversations. Shopping one institution means you get that institution’s answer, even if another wholesale lender would approve the same house on better terms.
As a broker we submit one application and compare the lenders we work with on pricing, overlays and timeline. You still close with a named lender. You just do not have to apply four times to find out who wants the file. That is the practical difference, and it is why buyers who start at a branch often end up calling us after the first denial or the first fee list they cannot explain.
How we take a Matthews purchase from conversation to keys
We begin with the house you have in mind and the payment you can live with, including taxes at the combined town rate if the parcel is inside Matthews. You complete one application. We look at pay, reserves and the credit report first, then issue a letter, because a listing agent in this market has seen too many letters that were only a soft pull and a guess.
Once you are under contract we choose the wholesale lender that prices your situation best, schedule the appraisal and work with you on lock timing. Underwriting runs while you finish inspections. You receive the Closing Disclosure with enough time to read it before the signing appointment, then you close with the lawyer you chose and the deed is recorded.
If you already own nearby and are deciding whether to sell first, keep reading below. If you are still comparing towns, Stallings and Weddington sit nearby, and the statewide purchase overview is useful if you are still choosing a city.
Reviews from people who financed with us
Clients leave these comments on Google. They are published here through our review feed, unedited, so you can read how closings actually felt.
Where the Matthews figures come from
Population, values, income, ownership, year built, tax bills and rent come from the Census Bureau’s ACS file covering 2020 through 2024, as compiled by Census Reporter. County listing activity for September 2026 comes from Realtor.com residential data. 2026 one-unit loan caps come from FHFA conforming limits and HUD FHA mortgage limits. Tax rates come from the North Carolina Department of Revenue’s published 2026-27 local rate tables. Contract practice follows the standard statewide REALTORS offer. The deed excise sits in Chapter 105 of the General Statutes. Flood maps come from FEMA. None of those sources is affiliated with 1st Advantage Mortgage.
A monthly payment in Matthews is more than principal and interest
Take a house with a $400,000 taxable value inside Matthews. Property tax at $0.7722 on each $100 of that value is about $3,089 a year, or roughly $257 a month before any exemption or appeal. Add homeowners insurance (quoted on the address, not a ZIP average), HOA dues if the subdivision or downtown townhome has them, and a flood policy if FEMA requires one. That stack, not the note rate alone, is what a Matthews payment looks like.
Because Mecklenburg’s next countywide revaluation takes effect in 2027, anyone closing in late 2026 should ask us to model escrow two ways: on today’s assessment and on a higher one. We would rather show you a conservative number now than have your servicer catch you up later.
If you already own a Matthews home
Owners here often want cash for a kitchen, a new roof or a second home closer to family, without replacing a first mortgage they are happy with. A home equity line can do that job when the combined loan-to-value fits investor guidelines. On published files we have seen qualified primary residences approved up to 95 percent combined loan-to-value. That is not a quote for your house. It is a reminder to look at a line of credit next to a cash-out refinance before you disturb a low first-mortgage rate.
Start with the Charlotte HELOC guide if you want to keep the first lien in place, or the statewide HELOC hub for North and South Carolina if you are comparing a line, a lump-sum equity loan and a refinance side by side. Buying a next house before this one sells is a different problem; that is the bridge HELOC conversation.
1st Advantage Mortgage Broker LLC is a Mortgage Broker, not a lender. Company NMLS #2468711 (NMLS Consumer Access), licensed as a mortgage broker by the North Carolina Commissioner of Banks. Equal Housing Opportunity. 1st Advantage Mortgage is not a government agency and is not affiliated with HUD, FHA, VA, USDA or any city or county. This page is general information, not an offer or commitment to lend. All loans are subject to credit approval, property appraisal and program eligibility, and program availability can change. Local statistics are estimates from the sources listed.