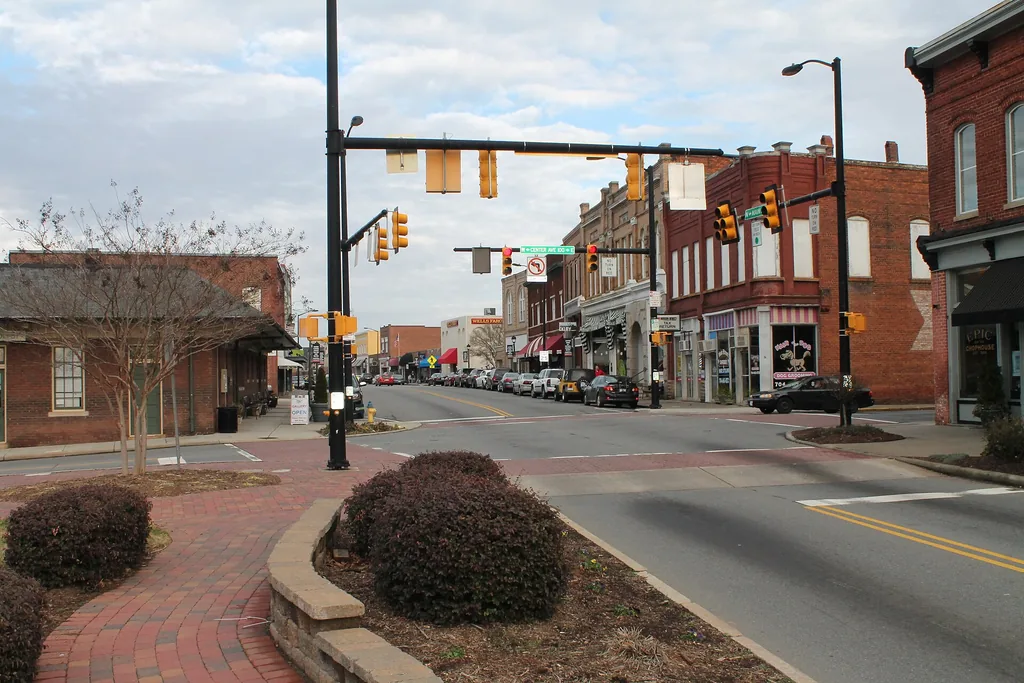
Mooresville grew up as Race City USA, home to Lowe’s corporate headquarters and many NASCAR teams, and it now stretches along Lake Norman’s western shore north of Charlotte. It is not in Mecklenburg County. The tax card, the school levy and the reappraisal calendar all say Iredell. Owner-occupied homes have a Census Reporter ACS midpoint (2020-2024) of $390,900, above Iredell’s $321,400. Household income centers on $89,647 versus $81,419 countywide. About 58 percent of households own, a lower share than the county’s 72 percent, so a large part of the demand we see is people moving out of rentals along the I-77 corridor.
Our office is at 128 South Tryon Street, suite 1933, in Charlotte. We are a North Carolina mortgage broker (Company NMLS 2468711). You apply once. From that application we price wholesale channels that regularly handle lake-access collateral, newer subdivision homes off NC 150 and NC 115, and townhomes near the interstate.
Race City is an Iredell town, even when the commute points south
Shoppers who already know Cornelius or Davidson sometimes treat Mooresville as the next Mecklenburg lake town. Underwriters do not. Iredell County last reappraised in 2023 and publishes its own rate. For 2026-27 the in-town stack is Iredell’s 50 cents plus Mooresville’s $0.4836 municipal levy, a published total of $0.9836 against each $100 of value, before any Mooresville Graded School District supplement. Scale that city-and-county piece to $400,000 and you land near $3,934. An extra $100,000 of assessed value raises the yearly city-and-county piece by about $984. The state’s 2026-27 rate tables are the source. A parcel beyond the town line loses the municipal piece.
Census Reporter counts 52,381 residents in Mooresville against 196,544 in Iredell County. Most Mooresville houses are newer than rural Iredell: the construction midpoint is 2006, versus 1997 countywide. Detached houses make up 60 percent of homes, below the county’s 71 percent, which matches what you see on the ground (more townhomes near I-77 than in rural Iredell). Three out of four owners still finance the house, well above the county’s 62 percent. Owners’ midpoint property-tax payment is $3,381, against $1,952 countywide. Gross rent centers on $1,626. Owners typically date their arrival to 2013.
Brawley peninsula, downtown, and the interstate townhomes
Lake Norman waterfront and the Brawley School Road peninsula are the files that regularly climb past FHFA’s 2026 conforming cap of $832,750. Those homes need a jumbo conversation, a flood-zone read, and a hard look at whatever sits at the water’s edge. A listing photo of a dock is not the same thing as a transferable permit. Duke Energy’s shoreline program, not the town, governs what can be placed along the lake.
Downtown mixes historic houses with newer infill near Main Street. Condition on the older stock and HOA or city-overlay questions on the new stock are the details that change the investor. Subdivisions off NC 150 and NC 115 are where many move-up buyers land, with more space for the money than a pier lot. Townhomes near I-77 are the usual entry point for first-time buyers. Neighboring guides include our Davidson page and the Iredell County overview.
The graded-school levy that does not appear on every card
Part of Mooresville is served by the Mooresville Graded School District, which levies its own supplemental tax on top of the $0.9836 city-and-county stack. The rest of town, and much of the surrounding county, is served by Iredell-Statesville Schools. The district line is not a trivia question. It changes both the school assignment and the tax bill. We confirm which district covers the house before we issue a payment letter, and we do not treat a neighbor’s bill as a substitute for that check.
Yearly billing dates and proration math are on the metro tax page. The local work is the graded-school question plus the town-limit question. Two houses with the same Mooresville mailing city can produce different escrow numbers once those lines are drawn correctly.
What Iredell's listings looked like this fall
Realtor.com put Iredell listings at a midpoint ask of $424,950 in September 2026, 6.5 percent under the prior year, and the typical listing needed 70 days. That month the county showed 1,008 homes for sale, about 3 percent above the prior September, along with 312 fresh listings and 412 pendings. More than a quarter of those listings already showed a reduced ask. Those counts cover all of Iredell, not a single pier lot on the Brawley peninsula or a brand-new street off NC 150.
Mooresville’s $390,900 owner midpoint sits a bit under that county asking-price snapshot and a bit above the county’s $321,400 owner-value midpoint. In plain language, town prices are richer than rural Iredell and more approachable than the most expensive Lake Norman waterfront. Loan-limit caps for 2026 appear on the conventional and FHA program pages; waterfront asking prices are the ones that regularly test the conforming threshold.
Financing a pier lot versus a house off NC 150
Away from the water, most files fit conventional or FHA financing. Veterans who qualify should weigh VA financing. On the peninsula and other waterfront streets, jumbo terms take over once the amount borrowed moves above FHFA’s 2026 conforming cap, and investors differ on how they treat shoreline property. Self-employed borrowers and business owners tied to the race shops or to other local firms can qualify using bank-statement documentation when a tax return is not the cleanest picture. Bonus or seasonal pay, which shows up on some corporate and team payrolls, belongs in the file before the pre-approval letter goes out.
Entry-level townhomes near I-77 are where cash-to-close help comes up most often. The programs our lenders run are not government grants. They are lender-written seconds or, less often, a grant next to a conventional loan. We put the helped quote next to a clean quote before anyone signs an offer.
Before the graded-school line, a $390,900 card at $0.9836 is about $3,845 a year
Mooresville’s published 2026-27 city-and-county stack is $0.9836, Iredell’s 50 cents plus the town’s $0.4836. Applied to the $390,900 owner midpoint, $0.9836 produces about $3,845 yearly, near $320 monthly. That figure is a floor, not a finished escrow, whenever the house sits inside the Mooresville Graded School District, because that district adds its own supplemental levy on top. We do not invent that supplement as a citywide number. We add it only after the parcel’s district is confirmed. Iredell-Statesville Schools cover other parts of town and do not add that extra line.
If the lot sits outside the town limit, only Iredell’s 50 cents remain, and the same $390,900 of value would owe about $1,955 a year, or about $163 a month. Mooresville’s $0.4836 town piece is about $1,890 at the midpoint. Owners’ ACS tax midpoint is $3,381, which sits below the $3,845 city-and-county worksheet and well above Iredell County’s $1,952. The survey response and the worksheet are different tools. Neither one replaces a graded-school check on the actual card.
Hold that $390,900 assessment next to Davidson’s Iredell-side pairing of $0.7760, which uses the same 50-cent county piece but only a 27.6-cent town levy. The Davidson pairing would collect about $3,033 a year on that value. Mooresville’s $0.9836 stack collects about $3,845, about $812 more, before any graded-school supplement. The extra town levy, not a different county, is doing that work.
Lowe's, race shops and Brawley: three files that do not share a program
Subtract Mooresville’s $390,900 owner midpoint from HUD’s $541,287 FHA maximum and about $150,387 remains. That room covers many resales off NC 150 and NC 115 and most entry-level townhomes near I-77. It does not cover many waterfront and Brawley School Road peninsula contracts that have already crossed FHFA’s $832,750 conforming cap and become jumbo files, with dock permissions governed by Duke Energy rather than by the town.
Household income of $89,647 sits about $8,228 above Iredell’s $81,419, while the owner midpoint of $390,900 sits about $69,500 above the county’s $321,400. Only about 58 percent of city households own, against 72 percent countywide, which matches the first-time demand along the interstate. Three out of four owners here still finance the house, well above the county’s 62 percent, and only 60 percent of homes are detached, below the county’s 71 percent. The typical house dates to 2006. Those figures describe a newer, more attached, more mortgaged town than rural Iredell, not a copy of a Cornelius or Davidson pier street.
Lowe’s headquarters and the local NASCAR shops are why bonus, overtime and seasonal pay show up in Mooresville files more often than in a bedroom town without those employers. That paper trail belongs in the first letter. A $541,287 in-town assessment at $0.9836 carries about $5,324 yearly, near $444 monthly. An $832,750 assessment carries about $8,191 yearly, near $683 monthly. Both figures still omit the graded-school supplement when that district applies. A Brawley jumbo file is where those larger illustrations start to matter. An I-77 townhome usually does not need them.
Docks, express lanes and the rest of the monthly budget
Two commute facts shape daily life more than they shape the note rate. Mooresville sits on I-77 at exits 31 through 36, and traffic toward Charlotte is heavy at peak hours. Tolled express lanes begin at exit 36, at the south end of town. The general-purpose lanes remain open; the toll is a budget line only if you choose those lanes.
The mechanics of a North Carolina purchase live in our purchase guide and closing-cost overview. What we do locally is confirm the graded-school line, read shoreline documents on lake lots, and build a payment that already uses Iredell’s $0.9836 stack whenever the lot sits inside the town limit. Once your offer binds the house we match an investor, arrange the appraisal (lake lots deserve extra care) and choose a lock date. Recording is handled in Iredell County. Anyone already living here who wants a new rate or term can use the Charlotte-area refinance page.
Mooresville and Lake Norman client remarks
The remarks that follow are Google reviews shown without our edits.
Where Mooresville's numbers are published
The ACS estimates on this page (2020-2024, via Census Reporter) cover 52,381 residents, income of $89,647, 58 percent ownership, a $390,900 owner-value midpoint, a 2006 construction midpoint, detached and mortgage shares, taxes paid of $3,381, rent of $1,626 and a 2013 arrival year, each set beside the matching Iredell County figure. Realtor.com reported Iredell’s September 2026 midpoint ask of $424,950 (down 6.5 percent), a 70-day typical listing, 1,008 actives (about 3 percent above the prior September), 312 new listings and 412 pendings, with price reductions already showing on more than a quarter of those listings. The 2026-27 rate tables list Iredell’s 50 cents, Mooresville’s $0.4836 and the $0.9836 total, and they name 2023 as Iredell’s latest reappraisal year. The $3,934 example applies those city-and-county rates to $400,000 of value. Lowe’s headquarters, the NASCAR-team presence, I-77 exits 31 through 36, express lanes beginning at exit 36, the Brawley School Road peninsula, Duke Energy’s shoreline program, and the split between Mooresville Graded School District and Iredell-Statesville Schools came from the page as it stood before this rewrite.
A Mooresville payment besides the note rate
Using $400,000 of in-town assessed value, the $0.9836 city-and-county stack produces about $3,934 a year. If the house sits inside the Mooresville Graded School District, a supplemental school tax sits on top of that number; we add it only after we confirm the district. Waterfront files should include a flood-zone read along with the dock questions. Association dues on newer streets off NC 150 or NC 115, and a premium an agent quotes for the actual address, complete the worksheet. See our insurance overview for how premiums are quoted in North Carolina.
Using Mooresville’s $390,900 owner midpoint, $0.9836 produces about $3,845 yearly, near $320 monthly, before any Mooresville Graded School District supplement. Beyond the town limit, Iredell’s 50 cents produce about $1,955 yearly, near $163 monthly. A $541,287 in-town card carries about $5,324 yearly, near $444 monthly. An $832,750 in-town card carries about $8,191 yearly, near $683 monthly. Those larger figures still leave out the graded-school line when that district applies.
If you already live in Mooresville
Lake parcels can hold equity well above the town’s $390,900 midpoint, and a jumbo first mortgage changes how that equity can be reached. A line of credit that leaves the first lien alone is often the cleaner starting point; read the comparison on our Charlotte HELOC guide. If you need to close on another house while this one is still yours, that discussion lives on the bridge page.
1st Advantage Mortgage Broker LLC is a Mortgage Broker, not a lender. Company NMLS #2468711 (NMLS Consumer Access), licensed as a mortgage broker by the North Carolina Commissioner of Banks. Equal Housing Opportunity. 1st Advantage Mortgage is not a government agency and is not affiliated with HUD, FHA, VA, USDA or any city or county. This page is general information, not an offer or commitment to lend. All loans are subject to credit approval, property appraisal and program eligibility, and program availability can change. Local statistics are estimates from the sources listed.