
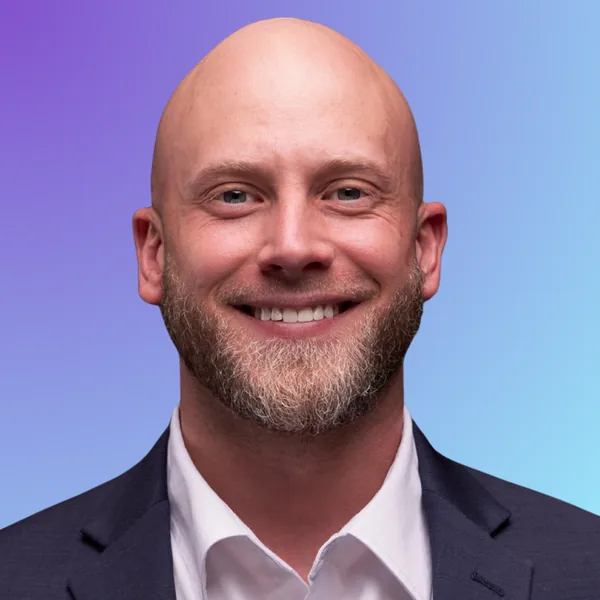
Michael Vittatoe wears two hats that matter to a buyer. He is a Managing Partner of 1st Advantage Mortgage, the independent brokerage housed in Suite 1933 of 128 South Tryon Street, uptown. He is also a practicing loan officer (individual NMLS 1906987) who still picks up the phone, reads credit reports and walks files to closing.
Most of the people who ask for Michael by name are buying or refinancing on the west side of the Charlotte metro, especially Gastonia, Belmont, Mount Holly, Dallas and Stanley. He also works files in Charlotte and Matthews. The geography is not a hard fence. It is where his week tends to land because that is where his clients and referral partners already are.
Why Gaston County files keep landing on his desk
Gaston County is close enough to Uptown that plenty of buyers treat it as a practical alternative to inside-the-loop Charlotte pricing, and far enough out that tax bills, school assignments and contractor norms feel local rather than generic. Michael has spent enough closings in Gastonia and the river towns to know that a Belmont address and a Dallas address are not interchangeable just because they share a county line.
That local reading shows up early. He wants to know whether you are stretching for a first house near downtown Gastonia, moving toward a larger lot in Stanley or looking at a refinance on a street you have lived on for years. Those three conversations do not produce the same document list, the same cash-to-close picture or the same set of wholesale lenders worth pricing.
If you are still choosing a town, the Gastonia home loan guide, the Belmont page and the Mount Holly page explain how taxes and inventory differ. Michael will use those details, plus the parcel itself, when he sizes a pre-approval.
What it means that he also helps run the firm
A Managing Partner title can sound like someone who has stepped away from daily origination. That is not how this office is set up. Michael still originates. The partnership role means he also helps set how 1st Advantage Mortgage works as a brokerage: one application, several wholesale lenders compared, a licensed officer who stays on the file, and support staff who handle processing details so the officer can stay with you.
Company NMLS 2468711 identifies the brokerage. Michael’s own record is 1906987. Those are different entries on NMLS Consumer Access, and both are worth opening before you apply. The company record shows where the firm may originate. The individual record shows where Michael himself is currently authorized. If a property sits outside his authority, he will say so and point you to a colleague rather than take an application he cannot finish.
The brokerage does not lend its own money. That is the point of calling a broker instead of a single bank. Michael’s job on your file is to line up the lenders the firm already works with, explain the tradeoffs in plain language and help you pick the path that fits the house and the monthly number you can live with.
Purchase work, refinances and the cash-out question
On a purchase, Michael starts with the payment you can carry, not just the price you saw online. Taxes, insurance and any association dues belong in that first conversation, because a Gaston County escrow stack does not look like a Matthews stack or a Fort Mill stack. He works conventional, FHA, VA, USDA, jumbo and investment-property financing, then prices more than one wholesale lender so you can see the difference on paper.
Eligible veterans should ask him to run a VA loan next to whatever conventional or FHA quote looked attractive, because the monthly picture can change once funding fees and occupancy rules are in view. First-time buyers often land on FHA or a low-down-payment conventional option; he will show both rather than picking a label in advance. A few wholesale partners offer their own cash-to-close help, usually recorded as a junior mortgage beside an FHA loan. One version fades away after you live in the house long enough. Another is paid back on a schedule. That help comes from the lender, not from a public agency, and he sets it next to a plain FHA scenario so any extra cost is obvious.
Homeowners call him about refinancing for a different reason: a rate they want to revisit, a cash-out idea or a loan they have outgrown. He reviews the current balance, equity and how long you plan to keep the house, then compares refinance offers and talks through the month when the costs would be earned back. If waiting is the better move, he will say that too. The refinance decision guide is a useful companion if you want to think it through before the call.
Agents, builders and the rhythm of a live contract
Michael works with real estate agents, builders and other referral partners on both sides of the Carolina line. The practical value is coordination. Listing agents in Gastonia can usually tell a carefully reviewed letter from a rushed pre-qualification that will not survive the first underwriter. He aims to issue the former, after pay, reserves and credit have actually been examined.
Once you are under contract, the file has a calendar. Appraisal, title, insurance and underwriting conditions all compete with your due diligence window. Michael stays on those dates with you and with the people around the transaction. Clients who have left Google reviews describe him as knowledgeable and responsive, and good at explaining options. One October 2026 reviewer wrote that he “made the mortgage process easy to understand.” Others credited him with helping them get into their new home. You can read the full set on our client reviews page.
Calling him, and what to have nearby
You can reach Michael directly at (704) 685-0235 or michael@firstadvantagemortgage.com. The form on this page goes to him rather than to a shared inbox. The main office number, 704-343-8681, reaches the firm if you are not sure who should take the file.
For a first conversation it helps to know the area you are shopping, a price range, how you earn income and whether the home will be a primary residence. Pay stubs, W-2s or tax returns, and recent bank statements speed up a pre-approval once you are ready. You do not need those documents just to ask a question.
If you would rather meet someone else on the roster, start with the full team list. James Scott, who also helps lead the firm, works many of the same west-side communities and is a good fit when schedules or licensing make that the cleaner match. The Charlotte purchase guide walks through the broader process if you are still early.