Home/Locations/Monroe
Union County, NC

Monroe Mortgage Broker and Lender

1st Advantage Mortgage is a licensed mortgage broker and lender in Charlotte, NC. Monroe homebuyers in Union County can compare loans near the US 74 corridor.

Monroe at a glance

Serving Monroe
Our full North Carolina licensed team
Programs
Conventional, FHA, VA, USDA, Jumbo and more
Typical pre-approval
24 hours
Office
About 40 minutes from Monroe in Uptown Charlotte

Also serving Indian Trail, Wingate, Marshville and Unionville.

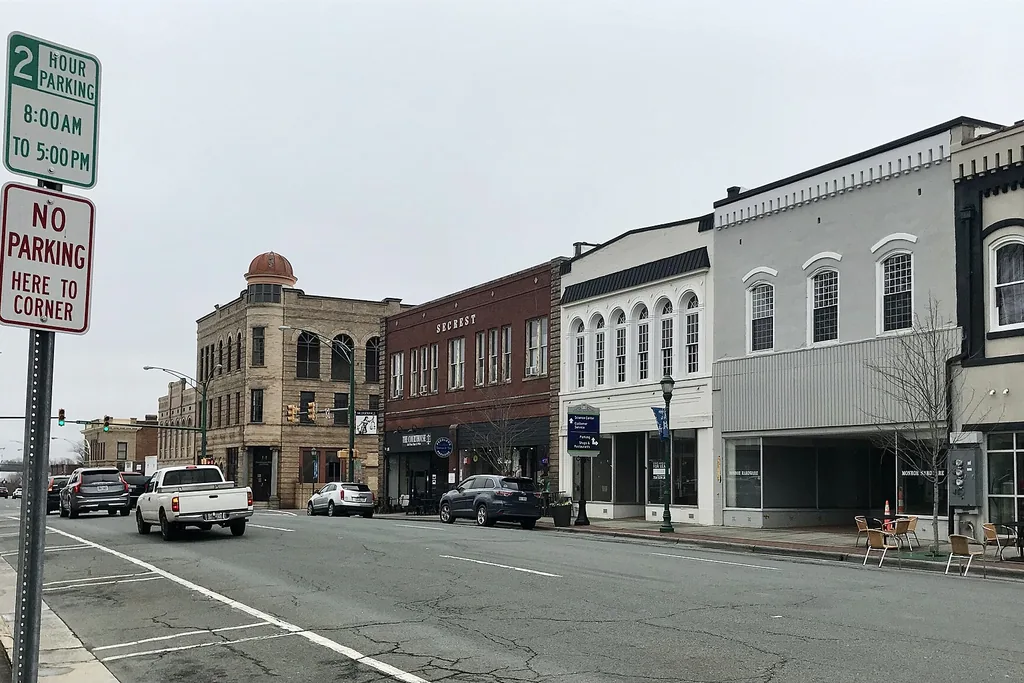
Monroe sits at the eastern end of the US 74 corridor, with the Monroe Expressway carrying through traffic around it and Charlotte Monroe Executive Airport on its edge. The housing runs from historic homes near the downtown square to new construction on the outskirts, which means two Monroe purchases can need quite different financing.

Our team works across Union County, NC and the wider Charlotte metro. As a mortgage lender and broker, we compare offers from multiple wholesale lenders on each file, so Monroe borrowers can review pricing, fees, and loan-program fit for the property they are considering.

Older homes and renovation financing

Buy near the Monroe historic district and you may be looking at a house that needs work before it is what you want. That is a financing question as much as a building one. A renovation loan rolls the purchase and the work into a single mortgage rather than leaving you to find the cash afterwards.

It is not the right answer for every house, and we will say so where a straightforward purchase is the cleaner route. But it is worth knowing the option exists before you rule out a property that needs a kitchen.

USDA eligibility around Monroe

Union County is one of the areas near Charlotte where USDA eligible addresses still exist, and a USDA loan can mean no down payment at all.¹ Eligibility is drawn by address rather than by town, and the maps change, so the only reliable answer is to check the specific property.

Send us an address and we will tell you the same day whether it qualifies. If it does not, we will put the realistic alternatives next to each other rather than leaving you to guess.

Loan programs for Monroe buyers

We place every program for Monroe borrowers. Each one has its own page with full eligibility detail. These are the short versions.

Program Best suited to Minimum down
ConventionalCredit and pricing vary by lender3%
FHAFirst-time buyers, lower credit3.5%
VAVeterans and active military$0⁴
USDAEligible addresses outside the metro core$0¹
JumboAbove the conforming limitVaries
InvestmentRental and second propertiesVaries
Adjustable-rateShorter expected ownershipVaries

Refinancing instead? We handle rate and term, cash-out and VA rate-reduction refinances and will show you the break-even before you commit.³

USDA loans around Monroe

Some areas around Monroe qualify for zero-down USDA financing. USDA eligibility is set by address rather than by town, so parts of Union County, NC qualify and parts do not, and household income limits apply. It is worth checking before you assume you need a down payment, and it takes us a minute to look up a specific address. Most lenders never raise it on a Monroe search. More on USDA home loans.
Your local team

Loan officers serving Monroe

Every North Carolina licensed loan officer on our team serves Monroe and Union County, NC.

See the whole team

Around Monroe

Neighborhoods and towns we lend in

Same team, same programs, same 24-hour pre-approval across Union County, NC. Before you write an offer, read what our clients say and our guide to getting approved for a mortgage in NC.

MonroeIndian TrailWingateMarshvilleUnionvilleWaxhaw
Questions

Monroe mortgage questions, answered

Are there USDA-eligible areas near Monroe?

Yes, in places. The map is drawn by address, not by town name, so two houses a mile apart in Union County, NC can get different answers, and there are household income limits on top. Send us the address you are looking at and we will tell you the same day whether it qualifies for zero down.

What down payment assistance is available to Monroe buyers?

North Carolina buyers can look at the NC Home Advantage Mortgage from the North Carolina Housing Finance Agency, which pairs a conventional, FHA, VA or USDA loan with down payment help for buyers who qualify. Every one of these has income and purchase price limits, and the limits change, so we check what you qualify for at the time you apply rather than quoting you a number today.

How long does closing take in Union County, NC?

Most purchases close in about 21 to 45 days from an accepted offer, and refinances are usually similar. Where you land in that range depends on the loan program, the appraisal and how fast documents come back. You get a timeline on day one and a call the moment anything moves it.

Can I get a VA loan in Monroe?

Yes. A VA loan works in Monroe exactly as it does anywhere else in North Carolina: no down payment for eligible veterans, service members and surviving spouses, no monthly mortgage insurance, and a VA funding fee that some borrowers are exempt from. Several of our officers write VA loans.

Is Monroe a good place to buy a home?

That is a question for a real estate agent rather than a mortgage broker, and we would rather say so than guess. What we can tell you is exactly what you can afford in Monroe, what the monthly payment looks like at today's pricing, and what it would take to be competitive on an offer. If you need an agent who works Monroe regularly, we can introduce you to one.

Do you work with first-time buyers in Monroe?

Yes, and a good share of our Monroe files are first-time buyers. We start with what you can comfortably afford rather than the maximum a lender will approve, walk through which program fits, and show you real closing costs before you start looking, so nothing at the table is a surprise.

Do you lend in Monroe?

Yes. 1st Advantage Mortgage is a licensed mortgage broker in North Carolina, and our loan officers licensed there can take your file. We handle both purchase and refinance in Monroe.

How fast can I get pre-approved in Monroe?

Usually within 24 hours of us having your information. We start with a short conversation about your goals, income and credit, then issue a pre-approval letter you can put in front of a seller.⁶

Are you a bank?

No, and that is the point. We are a broker, so we compare offers from multiple wholesale lenders on every file instead of fitting you to one institution's product. That covers conventional, FHA, VA, USDA, jumbo, investment and adjustable-rate programs.

What credit score do I need to buy in Monroe?

It depends on the program. FHA can go as low as 500 with a larger down payment, and 580 with 3.5% down. Conventional generally starts at 620, with pricing that varies by lender and borrower profile. We will tell you which programs you qualify for before you start looking.